Economic update Q4 2026
Uncertainty remains the watchword for the global economy, pushing up borrowing costs which is putting pressure on capital values. The supply/demand imbalance in the rental market continues to underpin rental growth.
The ongoing conflicts in Ukraine and the Middle East are contributing to uncertainty, and this, coupled with rising fuel costs, has put upward pressure on gilt rates, and increased the cost of borrowing for homebuyers and investors alike. There is continuing pressure on capital values and activity in the residential sales market as a result. Meanwhile demand in the rental market remains steady as supply is squeezed, underpinning rental rises.
Key facts:
- The cost of borrowing jumped in September as the US/Iran conflict remain unresolved. The rising cost of fuel, and increasing food prices, mean the Bank of England is preparing for inflation to rise to more than 4% next year
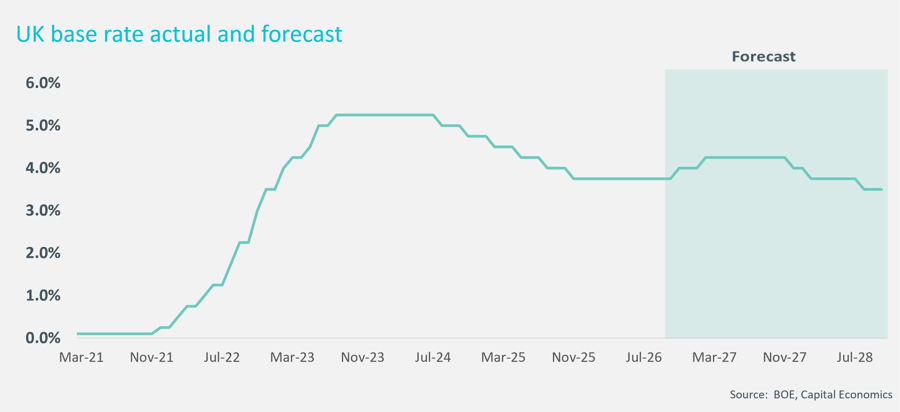
- A base rate rise on November 5th looks nearly certain, taking rates from 3.75% to 4%, and if hostilities persist, then another rate rise early next year is also looking likely
- Rising gilt yields are adding to the Government’s challenge as they approach the Budget, meaning they have less headroom to spend. Borrowing more to spend will not be popular with the financial markets, so this means the Chancellor will be considering tax rises. Labour’s manifesto pledge means they are unlikely to raise income tax, VAT or National Insurance for employees
- Average values for prime London homes have continued to decline, but deals are still being agreed, albeit they are progressing more slowly, with transactions most successful where vendors price their property in line with market conditions.
- Average rents in prime London rose again in Q3 as steady demand meets constrained supply, putting a floor under rental increases.
UK GDP rose by 0.1% in August. This modest increase was still higher than expected, and, along with recent monthly performances, signals that the UK economy has so far weathered the increased global uncertainty and rising prices more robustly than anticipated. The increase in economic activity was driven largely by the services sector, especially the AI, legal and advertising sectors.
A more resilient economy is good news, but it also means that worries about a fall in economic activity will be less of a factor when the Bank of England’s rate-setters meet on November 5th to decide on base rates.
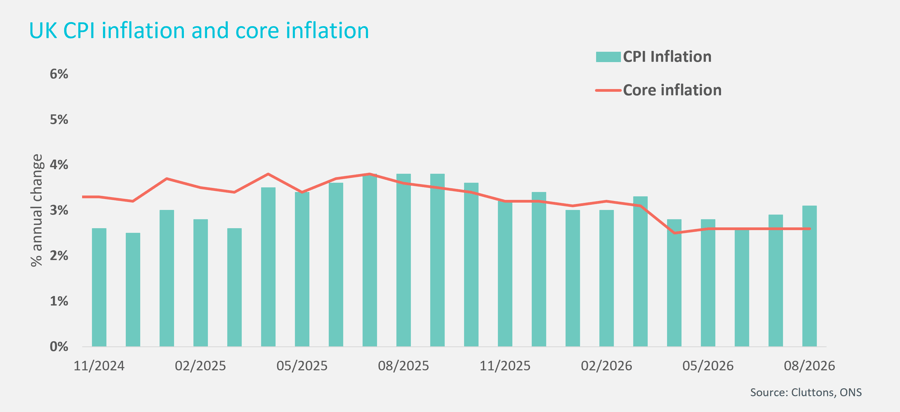
CPI inflation rose to 3.1% in August, up from 2.6% in June, even further above the Bank of England’s 2% target. Given the Bank has already forecast that inflation will peak at more than 4% at the start of next year, and with the ongoing conflict in the Middle East making the timing of the fall-back in inflation more uncertain, it is very likely that the rate-setting committee will vote to raise the base rate from 3.75% to 4%.
Base rates are forecast to rise again early next year, before starting to fall back towards the end of 2027.
Borrowing costs, which are linked to the money markets, have already risen sharply. 10-year gilt yields were around 4.3% at the start of March this year, and now they are sitting at 5.3%. This pushes up borrowing costs for the Government, but also mortgage rates for home buyers and investors. Several mortgage lenders re-priced their mortgage ranges upwards during September. However, a need to remain competitive to win business means that some lenders have started to trim their rates once more in October.
Rising mortgage rates are affecting budgets among home buyers, and uncertainty around the outlook has also led some potential purchasers to adopt a ‘wait and see approach’. The market is still active, with properties priced realistically moving more quickly.
The information provided in this report is the sole property of Cluttons LLP and provides basic information and not legal advice. It must not be copied, reproduced or transmitted in any form or by any means, either in whole or in part, without the prior written consent of Cluttons LLP. The information contained in this report has been obtained from sources generally regarded to be reliable. However, no representation is made, or warranty given, in respect of the accuracy of this information. Cluttons LLP does not accept any liability in negligence or otherwise for any loss or damage suffered by any party resulting from reliance on this publication.
Sign up to receive our research
Register here if you would like to receive our research direct to your inbox.
Cluttons produce quarterly research on both the residential and commercial markets. We also produce an annual report on the importance of digital connectivity and the infrastructure needed to provide it.