Prime London & UK sales market update Q4 2026
Prime London sales prices remain under pressure amid higher borrowing costs, tax changes and global uncertainty. Sales are being achieved where properties are listed at values reflecting the current market conditions. Across the UK, residential markets in the North continue to outperform.
Key facts:
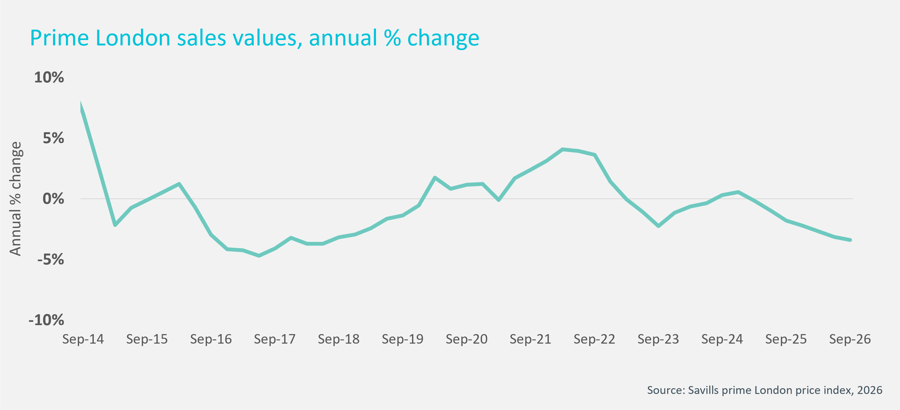
- Average prime London values are down -3.4% in the year to the end of September, and are down -7% from the most recent peak in prices in late 2022
- The decline in prime central London prices is more pronounced, with flats down 13% over the last 4 years, and falling 5.5% in the last 12 months, and houses down 10% since 2022 and 4% since September last year
- The downward pressure on pricing from higher borrowing costs and past and future tax changes is still feeding through, and we now expect prime London prices to be down by -2.5% at the end of the year, followed by a slight bounce-back of +1% next year
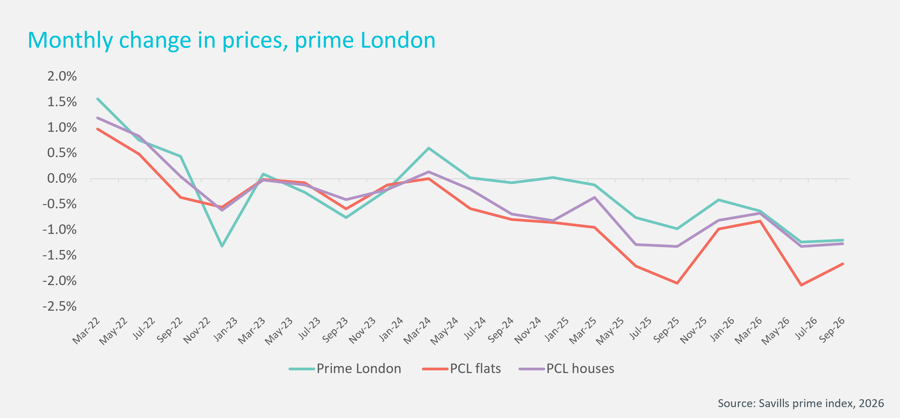
Average prime London home values fell by -1.2% in Q3, matching the -1.2% decline in Q2, and taking the fall since January to -3%. On an annual basis, prime London prices are down -3.4%.
In the prime central London (PCL) market, greater geopolitical uncertainty is making discretionary buyers more cautious, and in some cases extending the time needed to complete deals. The market is still adjusting to the non-dom reforms, particularly the inheritance tax changes introduced last year, which have already led some owners to leave the UK.
Yet London remains a draw for global investors and buyers given the capital’s amenity, lifestyle and educational advantages, which means there is activity in the market, but there are signals in the market that some overseas buyers who would traditionally have purchased a home are choosing the rental market.
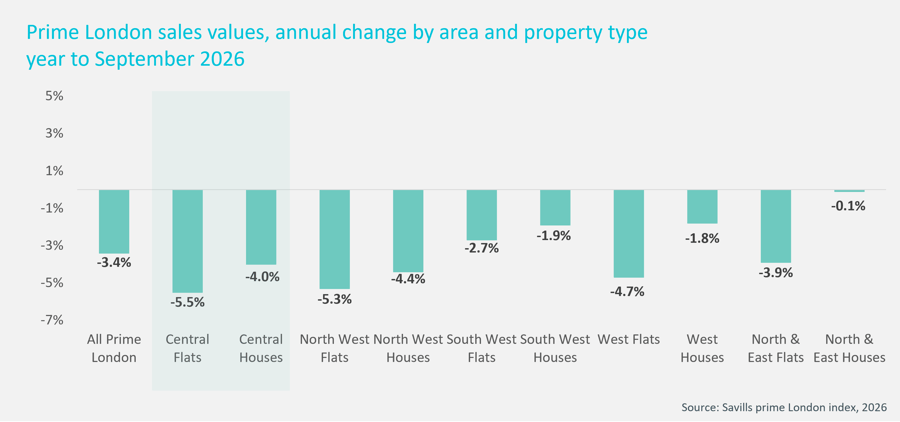
Average prices in the prime central London market are down by -4.7% on the year, with a -5.5% decline for flats and a -4.0% fall in the average price of houses. This mirrors a trend across wider prime London, that the market for flats is more challenging than houses. There are several factors underpinning this, including the increased prominence of service charges as a consideration in price, increased fire safety regulation for tall residential towers introduced after the tragedy of the Grenfell fire in 2017. This increased regulation, and the delays in inspections and remediations needed, have made it more challenging to secure mortgage finance in some cases. Another issue is the rental market. As landlords have exited the market due to increased regulation, and reduced numbers of smaller landlords are entering the market, the availability of flats for sale has risen.
Average values for prime central London flats have fallen by 31% since the peak of the market in 2014, compared to a 23% decline in house prices.
Average price changes in the more domestically-driven prime markets outside PCL are less pronounced, with average values for houses in the North and East, around the East of the City and up into Islington, broadly unchanged on the year. The market will also be absorbing upcoming tax changes in pricing.
From April 2028, properties valued at £2m or above will be subject to the Higher Value Council Tax Surcharge (HVCTS). The annual levy will range from £2,500 to £7,500. While it has been described as a mansion tax, earlier proposals envisaged an uncapped charge equal to 1% of a property’s value, making the confirmed surcharge a much more limited measure. Even so, this tax may act as another drag on pricing for homes worth more than £2m next year, but if interest rates start to fall back at the end of next year as forecast, this will provide a boost to the market.
Given the continued economic uncertainty and sharp upward pressure on borrowing costs since our last update in July, it is now more likely that the outcome for the year will be to the downside of our previous forecast for a -1.5% fall, closer to -2.5%.
UK housing market
In the wider UK housing market, annual price growth slid to 1.2% in Q3 compared to 2.2% in Q2, according to the quarterly annual price index from Nationwide.
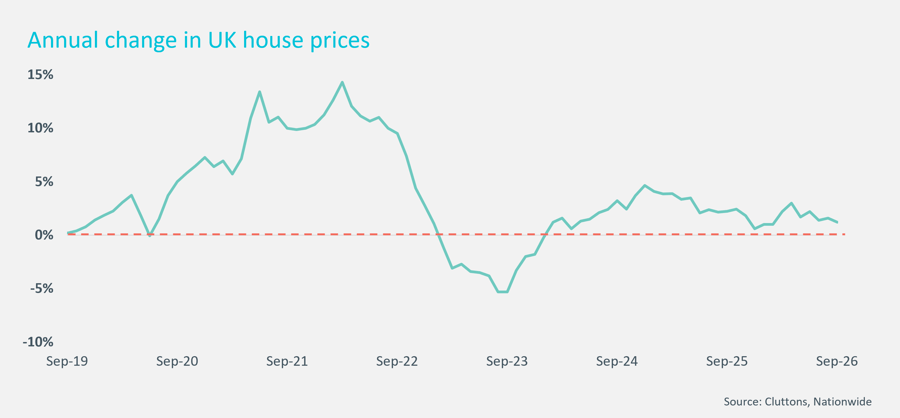
This continued easing in prices again reflects the wider market uncertainty, and the sharp rise in mortgage rates during September. As in prime London, the value of houses outpaced that of flats – terraced houses performed most strongly, registering a 1.8% rise in prices over the year, compared to a 0.1% rise in the average price of a flat.
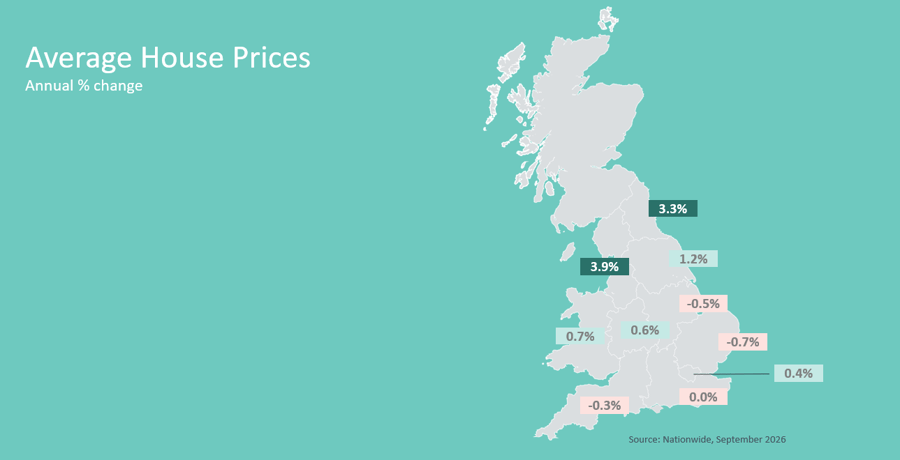
The regional picture shows a clear north–south divide in house price performance. Prices fell across East Anglia, the East Midlands and the South West, by 0.7%, 0.5% and 0.3% respectively, while the South East was unchanged and London recorded growth of just 0.4%. In contrast, the North West led the market with annual growth of 3.9%, followed by Scotland and the North East, both at 3.3%. Elsewhere, growth was more modest, at 1.2% in Yorkshire and the Humber, 0.7% in Wales and 0.6% in the West Midlands. This continued outperformance of more affordable northern markets suggests that higher mortgage costs are having a greater impact on prices across southern England.
Forecast
| Year | UK House Prices | Prime London Prices | Prime Central London Prices |
|---|---|---|---|
| 2025 | +1.7% | -2.2% | +2.1% |
| 2026 | +1.5% | -2.5% | +3.0% |
| 2027 | +3.5% | +1.0% | +3.0% |

The information provided in this report is the sole property of Cluttons LLP and provides basic information and not legal advice. It must not be copied, reproduced or transmitted in any form or by any means, either in whole or in part, without the prior written consent of Cluttons LLP. The information contained in this report has been obtained from sources generally regarded to be reliable. However, no representation is made, or warranty given, in respect of the accuracy of this information. Cluttons LLP does not accept any liability in negligence or otherwise for any loss or damage suffered by any party resulting from reliance on this publication.
Sign up to receive our research
Register here if you would like to receive our research direct to your inbox.
Cluttons produce quarterly research on both the residential and commercial markets. We also produce an annual report on the importance of digital connectivity and the infrastructure needed to provide it.